Straight facts. No spin.
Short reads on the messy reality of personal finance. State-level payday rules, APR math without the brain fog, earned wage access, repayment strategies, and the small habits that make a tight month less tight.

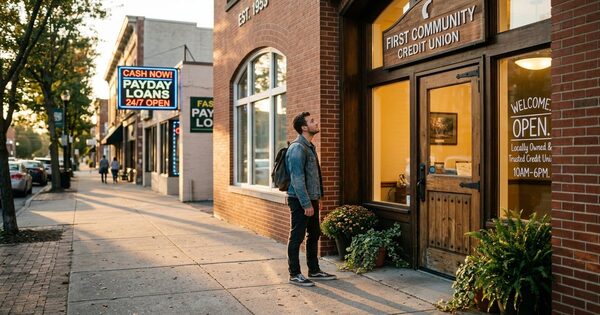
The 28% Loan Most Payday Borrowers Have Never Heard Of
Federally regulated credit unions can offer a Payday Alternative Loan capped at 28% APR with a $20 fee. Here is how to find one and what to do when your credit union does not offer them.

How to Save Your First $1,000 (When You Are Living Paycheck to Paycheck)
Skip the "six months of expenses" cliche. A real plan that starts at $250 in 12 weeks, hits $1,000, and explains why crossing that line changes everything else.
Why We Will Never Send You to a Title Loan (and 5 Better Options)
One in five auto-title loan borrowers loses the car. We do not route any borrower to title lenders. Here is the safer place for every reason people end up there.
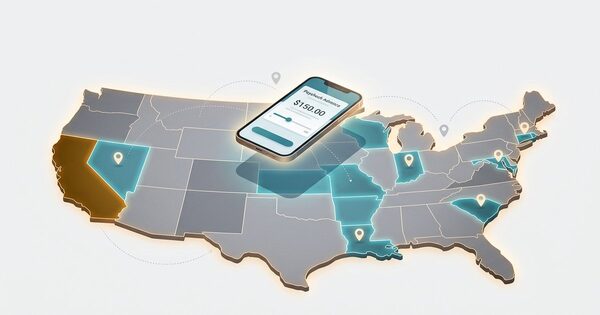
Paycheck Advance Apps in 2026: What Is Actually Legal in Your State
Same app, different rules. California treats EWA as a loan, other states let it run, others do not regulate it at all. Here is what your state allows in 2026.

That '391% APR' Loan Might Actually Cost You $45. Here Is the Quick Math.
A scary APR on a short-term loan does not mean what you think it means. A four-line check that turns the disclosure box into a real dollar total in under a minute.

Before You Borrow, Ask HR: 5 Things Your Job Might Already Pay For
Hardship grants, employer-sponsored EWA, 401(k) loans, and the SECURE 2.0 emergency withdrawal. Often free or much cheaper than a short-term loan, and almost nobody asks.

The Right Checking Account Can Save You $400 a Year. Here Is How to Pick One.
The wrong checking account costs you in overdraft fees, slow deposits, and rejected loan applications. Here is the setup borrowers actually need before they apply.

Active Duty? Your Loan Cap Is 36%. Here Is What Actually Counts.
The Military Lending Act caps the all-in cost of most consumer credit at 36% for active-duty borrowers. Here is who is covered, what is excluded, and where lenders still try to charge more.

Cash Advance App or Eat the Overdraft? The Surprising Answer Depends on the Amount
For some shortfalls a $35 overdraft is the cheaper move. For others the cash advance app wins. The side-by-side math nobody puts in the same paragraph.